Homepage concepts we've designed for mortgage brokers
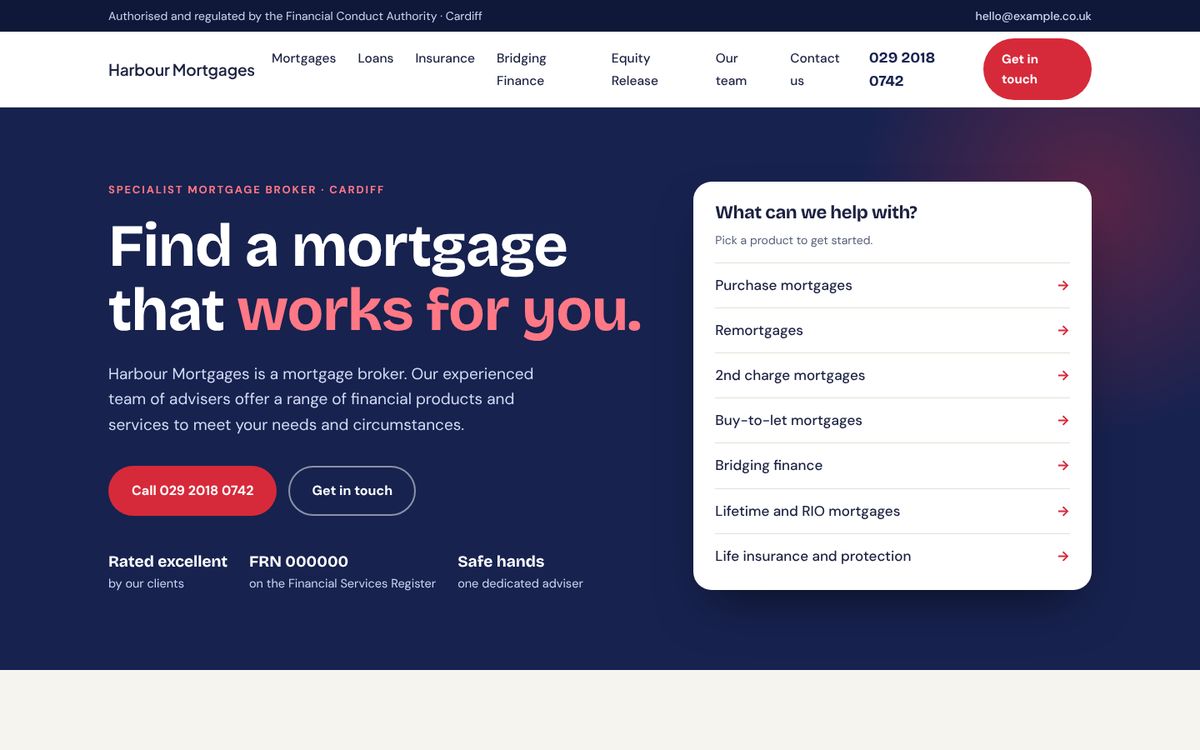
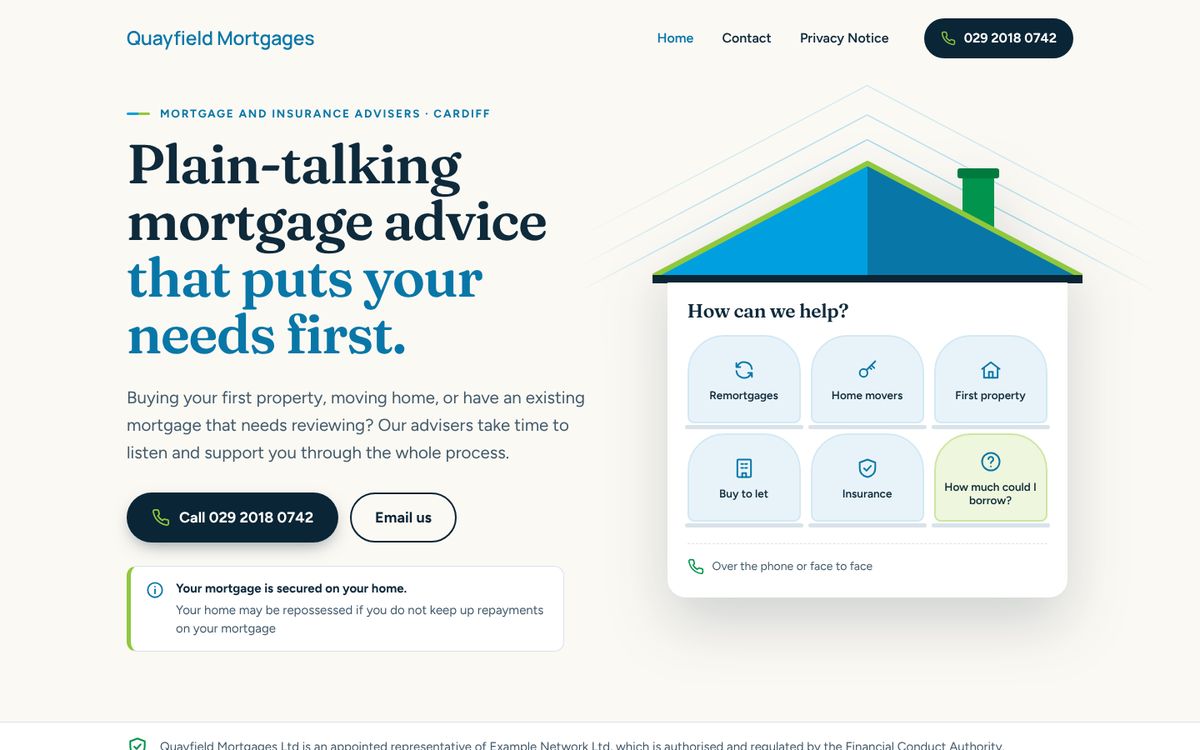
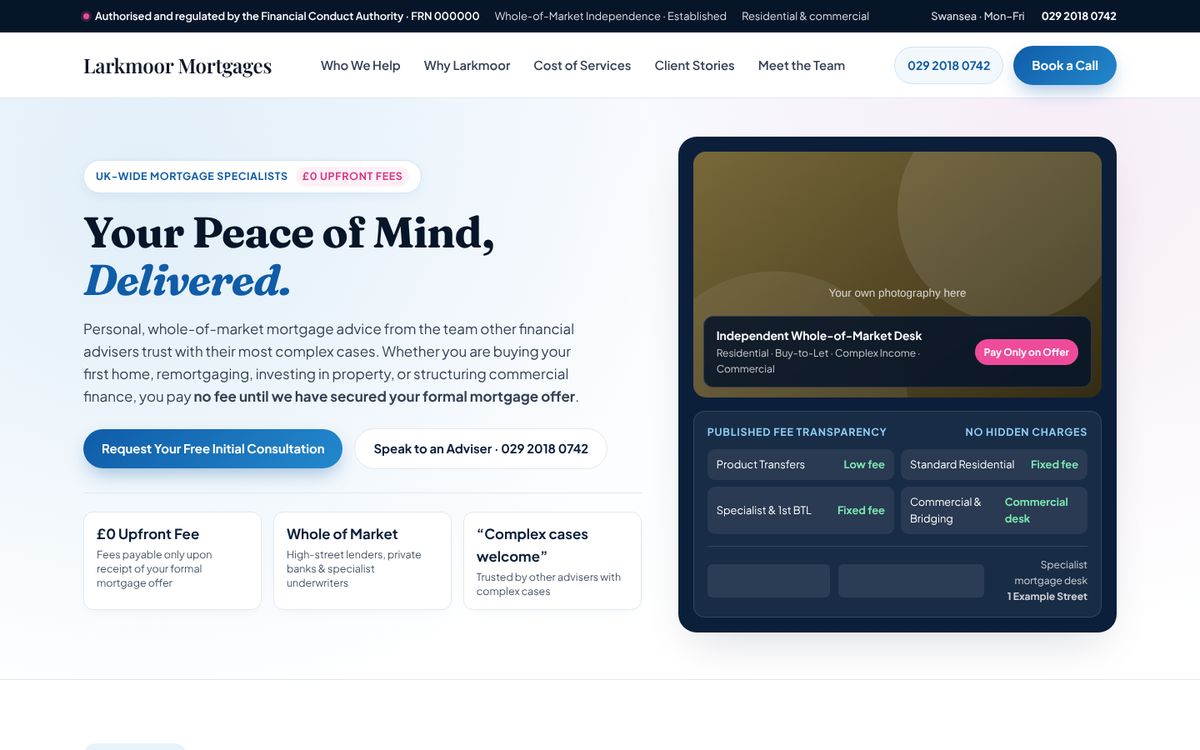
Three concepts for South Wales brokers: a whole-of-market specialist, an appointed representative of a network, and a fee-transparent complex-case desk. Names, people, photos, contact details and other identifying details have been changed, and reference numbers replaced with zeros.
What a mortgage broker's website has to show
The FCA treats a website as a financial promotion: it must be fair, clear and not misleading. These are the points we build in, ready for your compliance team or network to sign off.
Status and reference number
Your name, address, contact details, VAT number if registered, the statutory status statement and a statement that you're on the Financial Services Register with your firm reference number, all "easily, directly and permanently accessible". We put them in every footer. Appointed representatives use the "is an appointed representative of…" wording, and the regulator's name must be written in full, not as "FCA".
Secured lending and risk
Promotions must make clear, where it applies, that the loan is secured on the customer's home, and give a fair and prominent indication of the risks. The old "your home may be repossessed" line is no longer prescribed wording, but many brokers keep it as their risk warning, and we lay out whichever wording you sign off.
Careful with rates
Quoting a rate or cost triggers extra requirements, including a representative example and the APRC shown at least as prominently as the interest rate. We design pages to work without rates, and add them only when your compliance team has approved the example.
Fees and "independent"
Brokers must disclose their fees, when they're payable and how commission works. A clear fee page helps meet that and wins trust. You should only call yourself an "independent mortgage adviser" if your range across the market is unlimited.
Complaints and the Ombudsman
Firms must give information about the Financial Ombudsman Service, including its website address, on their own website, along with how to complain to you.
Unregulated lending, labelled
Most buy-to-let, commercial and bridging loans aren't FCA-regulated mortgage contracts (consumer buy-to-let has its own rules). Pages for them must not imply regulation that doesn't apply, so we label them clearly and keep them separate from regulated mortgage pages.
Sources: FCA: financial promotions and adverts · MCOB 2 · MCOB 3A · MCOB 4 · GEN 4 · DISP 1. A summary as of November 2026, not compliance advice; your compliance team or network signs off the final wording.
Protect your clients from clone firms
The FCA warns that clone firms copy genuine brokers' websites and reference numbers, changing just the phone number. Your website can make that harder to pull off.
Matching contact details
The phone numbers and email addresses on your site match your FCA register entry exactly, so a client who checks gets a match.
"Check us" link
A link to your entry on the FCA's Firm Checker, so clients can confirm you're genuine in one tap.
Email that can't be faked
AlphaSec sets up SPF, DKIM and DMARC so nobody can send convincing emails from your domain.
Source: FCA: clone firms and individuals.
What borrowers search for, and what your site needs for each
| Borrower | Typical searches | What we build |
|---|---|---|
| First-time buyers | "first time buyer mortgage advice Cardiff", "how much can I borrow" | A first-time buyer guide that explains the process and hands over to an adviser. |
| Remortgaging | "remortgage broker Wales", "my fixed rate is ending" | A remortgage page with a "book a review" form timed around fixed-rate end dates. |
| Self-employed | "self employed mortgage broker", "mortgage with one year accounts" | Specialist-case pages that show you handle complex income. |
| Landlords | "buy to let mortgage broker" | Clearly labelled buy-to-let pages, kept apart from regulated mortgage pages. |
| Checking you out | "do mortgage brokers charge a fee", "is my mortgage broker FCA registered" | A fee page and a regulatory information page, both linked from every footer. |
See your new homepage first, free
- Free homepage concept
Enter your work email. We redesign your homepage and send you a private link, usually within a day. No call, no obligation.
- £495 to build the rest
Like it? We build the full site, move your existing pages and regulatory information across, and redirect your old addresses to protect the Google rankings you've earned.
- £69 a month, changes included
Hosting, security, backups and updates. New starter, new fee table, new office: email us and it's done.
- Optional £49/month SEO
Automated weekly SEO checks your site every week and makes small updates to keep it visible in Google and AI search.
Part of a network? We work with your network's compliance team and keep a record of which version of each page they approved.
Common questions from mortgage brokers
Who signs off the website wording?
You do, or your network's compliance team. We build in the FCA status statement, register details and risk wording, and nothing goes live until it's approved.
Do we have to use "Your home may be repossessed"?
The FCA's rules no longer prescribe that exact sentence, but you must make clear that a mortgage is secured on the home and give a fair and prominent indication of the risks. Many brokers keep the familiar wording; your compliance team decides.
Can we show rates on the website?
You can, but quoting a rate brings extra requirements such as a representative example and the APRC. Most broker sites work better without live rates, and we add them only with compliance approval.
We're an appointed representative. Is that a problem?
Not at all. We use your network's required status wording and work with their compliance process.
How much does it cost?
The homepage concept is free. The full site is £495, then £69 a month for hosting, security and changes, including updates your compliance team asks for.